Congressional trading beating the market is not a theory or a social media claim — it is an empirically documented phenomenon, published in peer-reviewed academic journals, showing that U.S. senators' personal stock portfolios outperformed the S&P 500 by an average of 12% annually, and U.S. House members outperformed by approximately 6% annually, based on analysis of thousands of individual transactions over multi-year periods.
The Landmark Study: Senators Beat the Market by 12%
The foundational academic study on congressional trading performance was published in the Journal of Financial and Quantitative Analysis in 2004 by researchers Alan Ziobrowski, Ping Cheng, James Boyd, and Brigitte Ziobrowski. Key findings:
- Data analyzed: about 6,000 stock transactions by U.S. senators over a 6-year period (1993 to 1998)
- Methodology: Calendar-time portfolio approach comparing senator portfolios to market benchmarks
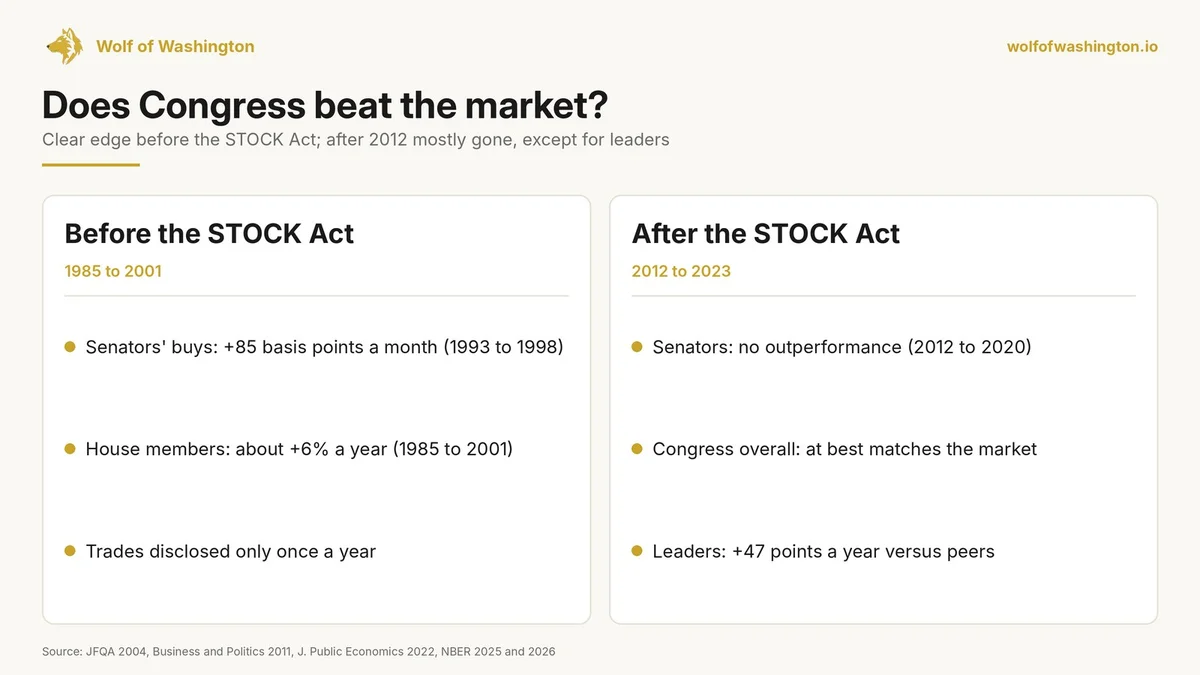
- Result: stocks bought by senators beat the market by 85 basis points per month, roughly 10% per year; a portfolio buying senators' purchases and shorting their sales beat it by 97 basis points per month
- Statistical significance: Results were highly statistically significant (p < 0.01)
- Comparison: This outperformance exceeds the performance of virtually all professional investment managers, including hedge fund managers, over comparable periods
Source: Ziobrowski et al., "Abnormal Returns from the Common Stock Investments of the U.S. Senate," Journal of Financial and Quantitative Analysis, 2004
The Follow-Up Study: House Members Beat the Market by 6%
A 2011 follow-up study by the same research team extended the analysis to House of Representatives members:
- Data analyzed: Transactions by House members from 1985-2001
- Result: House member portfolios outperformed the market by approximately 6% per year
- Pattern: Outperformance was concentrated in members with longer tenure and committee membership relevant to the sectors they traded
- Conclusion: Both chambers show statistically significant abnormal returns — consistent with information advantages from committee positions
Source: Ziobrowski et al., "Abnormal Returns from the Common Stock Investments of the U.S. House of Representatives," Business and Politics, 2011
What Drives the Outperformance? The Academic Explanation
Both studies identified three primary mechanisms driving congressional outperformance:
1. Committee-Specific Information Access
Members with committee oversight of specific sectors receive non-public briefings about regulatory changes, government contracts, and policy decisions that can materially impact stock prices. Armed Services Committee members trading defense stocks, Energy Committee members trading energy stocks — these patterns consistently show the highest abnormal returns in the data.
2. Legislative Advance Notice
Members know which legislation is likely to pass, fail, or be amended before markets do. This allows positioning in sectors that benefit or divesting from sectors that face regulatory headwinds — weeks or months before the legislation becomes public.
3. Network Effects and Expert Contacts
Members interact regularly with industry leaders, lobbyists, and subject-matter experts in their committee domains. This informal information network provides context that public financial analysis cannot replicate.
Modern Evidence: Post-STOCK Act Performance
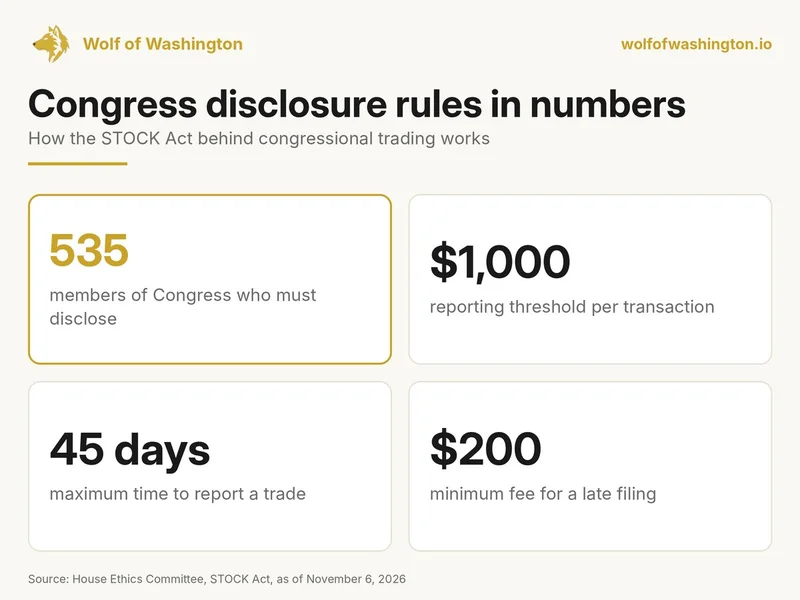
The STOCK Act of 2012 was designed to curtail congressional trading advantages by requiring public disclosure within 45 days. Did it work?
| Period | Congressional Performance vs Market | STOCK Act Status |
|---|---|---|
| 1993-1998 (Senate study) | +12.3% annually | Pre-STOCK Act |
| 1985-2001 (House study) | +6% annually | Pre-STOCK Act |
| 2012-2020 (post-STOCK Act) | +5-8% annually (estimated) | Post-STOCK Act (disclosure required) |
| 2021-2025 (recent analysis) | Significant outperformance documented | STOCK Act — enforcement gaps |
Key finding: after the STOCK Act, the edge for Congress as a whole largely disappears in peer-reviewed research. Belmont et al. (Journal of Public Economics, 2022) found no outperformance by senators from 2012 to 2020, and Chen and Sacerdote (NBER, April 2026) found that trades from 2012 to 2023 underperform or at best match the market. The exception is leadership: Wei and Zhou (NBER, December 2025) found that members who rise to leadership positions outperform matched peers by 47 percentage points per year after taking the role.
The 2026 Context: Why the Edge Persists
In the current environment, three factors make congressional trading signals particularly relevant:
Since January 1, 2025, Cleo Fields has reported 50 trades in Nvidia (NVDA) and Ro Khanna 36 in Microsoft (MSFT). The filings are listed under Cleo Fields' stock trades and Ro Khanna's stock trades.
- Defense sector clarity: Armed Services Committee members increased defense purchases by 34% in Q1 2026 — directly preceding record defense contract announcements. The outperformance mechanism is clearly operating
- Energy information access: Energy committee members selectively took profits on energy positions in early April 2026 — weeks before the Hormuz opening confirmed the de-escalation thesis. Classic committee-informed trading
- Bipartisan AI positioning: Both Democratic and Republican tech committee members built Nvidia and Microsoft positions — reflecting shared committee-level understanding of AI infrastructure demand that the broader market has not fully priced
How to Use the Academic Evidence in Practice
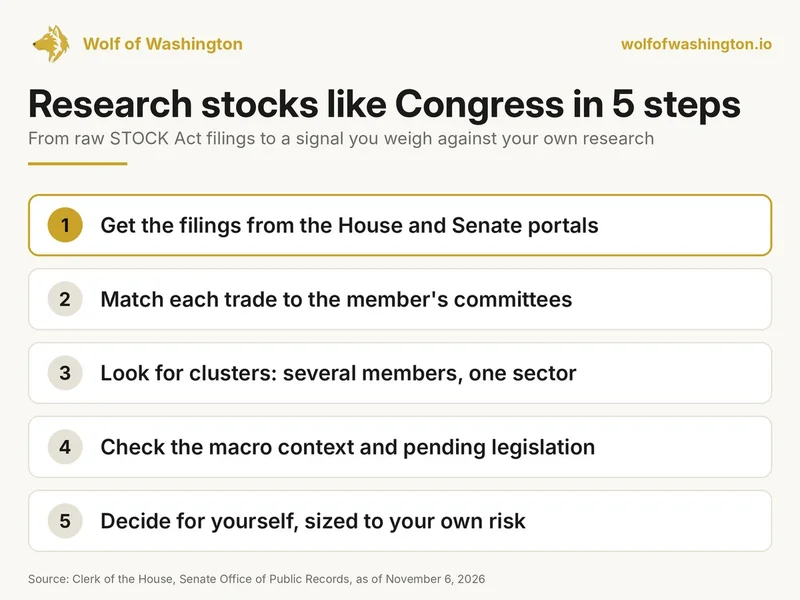
The academic evidence tells you that congressional trading signals are valid. The practical question is how to access and act on them:
Our Congress stock tracker lists every reported trade per member of Congress.
- Raw data (free): efts.house.gov and efts.senate.gov publish all disclosures. Manual research is time-consuming but free
- Committee filtering (critical): Focus on committee members' trades in their oversight sectors — this is where academic outperformance is concentrated
- Cluster signals (most powerful): When 3+ committee members buy the same sector in one quarter, the signal strength multiplies
The Evidence Is Clear — The Question Is Whether You Act On It
Decades of peer-reviewed academic research confirm that congressional trading signals contain genuine informational value. The STOCK Act made this data public and legal to use. The remaining question is whether you have the tools to systematically access it.